If you’ve recently dealt with storm damage or noticed your roof is showing its age, you’ve probably asked yourself: will my homeowners insurance cover this? It’s a fair question, and the honest answer is: it depends. Your policy may cover some situations completely, partially, or not at all, and knowing the difference can save you thousands of dollars.
Let’s break down what homeowners insurance actually pays for when it comes to your roof and what it typically won’t touch.
How Homeowners Insurance Handles Roof Damage
Most standard homeowners insurance policies cover roof damage that results from a sudden, unexpected event. Think major windstorms, hail, falling trees, or fire. If your roof shingles were torn off during a storm last night, that’s the kind of scenario your insurer had in mind when they wrote your policy.
The key phrase here is “sudden and accidental.” Insurance is designed to protect you from events you couldn’t predict or prevent, not from the gradual effects of time.
What Types of Roof Damage Are Usually Covered?
Storm and Hail Damage
Hail is one of the most common reasons homeowners file a roof insurance claim in Spokane.
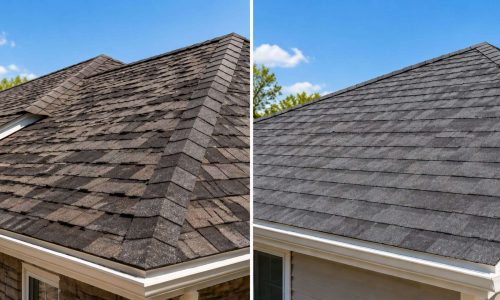
Those ice pellets can crack, bruise, or knock granules off your roof shingles, compromising their ability to protect your home. Most insurance policies treat hail as a covered peril, especially when there’s visible, documented damage.
Wind damage falls into the same category. If a strong windstorm lifts or tears away sections of your roof, your home insurance policy should respond – assuming you’ve kept up with basic maintenance and the damage wasn’t already present.
Falling Objects and Fire
A tree branch crashing through your roof during a storm is typically a covered event. So is fire damage. These are clear-cut cases where the cause is sudden and outside your control. Your insurer will usually send an adjuster to assess the damage and determine your payout based on your policy terms.
What Homeowners Insurance Usually Does Not Cover
Wear and Tear
This is where a lot of homeowners get caught off guard. If your roof is simply aging – losing granules, developing small leaks from years of exposure, or showing signs of general wear – your insurance policy won’t cover the replacement. Wear and tear is considered a maintenance issue, not an insurable event.
Insurance companies expect you to maintain your home. If a leak develops because your roof was already in poor condition before a storm hit, the insurer may deny part or all of your claim.
Flood Damage
Standard home insurance policies do not cover flooding. If water comes up from the ground and damages your roof or attic structure, you’d need a separate flood insurance policy to recover those costs. This surprises a lot of homeowners who assume their policy covers all water damage.
Neglect and Deferred Maintenance
If your roof had known problems that you didn’t address, and those problems led to further damage, your insurer may argue that negligence was a factor. Document everything with photos and videos, and address minor repairs promptly to protect yourself when it’s time to file a claim.
Actual Cash Value vs. Replacement Value: What’s the Difference?
This distinction matters a lot. Some insurance policies pay out based on replacement value, meaning they’ll cover what it costs to replace your roof with a comparable new one. Others pay actual cash value, which factors in depreciation.
If your roof is 18 years old and an actual cash value policy is in play, you might receive only a fraction of the actual replacement cost. A 20-year-old roof that would cost $12,000 to replace might only net you $4,000 or $5,000 after depreciation is applied.
Before you file a claim, it’s worth reviewing your policy documents carefully or calling your agent to understand which method your policy uses.
Understanding Your Deductible
Your deductible is the amount you pay out of pocket before your insurance kicks in. If your deductible is $2,500 and the estimated damage is $3,000, your insurer would only pay $500. In some cases, the payout barely covers the cost, and you’re still responsible for most of the work.
Some policies also carry a separate hail or wind deductible that’s calculated as a percentage of your home’s insured value – not a flat dollar amount. That can add up quickly on higher-value properties.
How to Strengthen Your Insurance Claim
If you believe you have covered damage, here are a few practical steps that can make the claims process smoother:
- Document everything with photos and videos immediately after the damage occurs.
- Avoid making permanent repairs before an adjuster has reviewed the damage.
- Get a written assessment from a reputable local roofer who understands what insurers look for.
- Keep records of any past maintenance or repairs you’ve had done.
Working with an experienced roofing contractor before and during the claims process gives you a clearer picture of what you’re dealing with. A qualified roofer can help identify damage you might not notice from the ground and provide documentation that supports your claim.
When a Full Roof Replacement Makes Sense
Sometimes a repair isn’t enough. If your roof has multiple areas of damage, aging shingles, or compromised underlayment, a full roof replacement may be the more cost-effective long-term decision – even if insurance only covers a portion of the cost.
Balsamroot Exteriors works with Spokane homeowners to assess roof conditions honestly and help them understand their options before they commit to anything. Whether you’re navigating a claim or simply planning ahead, having a clear picture of your roof’s condition is always the right starting point.
If you’re thinking about what comes next, learning more about roofing replacement is a practical first step.
What Homeowners Insurance Really Pays for on a Roof
Homeowners insurance can cover roof replacement – but only under the right conditions.
Sudden weather events like hail and wind are typically covered, while wear and tear, flood damage, and neglect are not. Understanding your deductible and whether your policy pays replacement value or actual cash value makes a significant difference in what you actually receive. If you suspect storm damage or want a professional eye on your roof before filing a claim, reach out to Balsamroot Exteriors at 509-295-2326 for an honest assessment.